
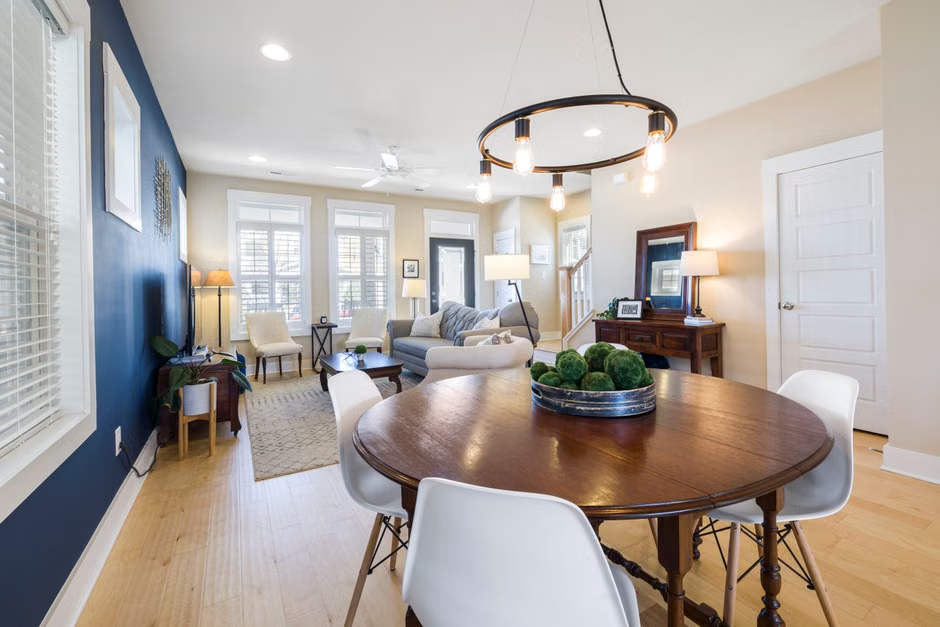
If you own a condominium in Miami, you likely know that your association carries a master insurance policy. What many owners do not realize is that this policy typically covers only the building’s exterior, common areas, and grounds. Your personal property, interior walls, fixtures, and liability are your responsibility. That is why a personal condo unit insurance policy, officially known as an HO-6 policy, is essential. This article explains what condo unit insurance in Miami covers, why it costs more in Florida, how major insurers compare, and how to close coverage gaps.
What Does Condo Unit Insurance Cover?
An HO-6 policy is designed specifically for condo owners. It bundles several key protections that the association’s master policy does not provide.
Personal Property and Liability
Your personal belongings inside your unit, such as furniture, electronics, clothing, and appliances, are covered against named perils like fire, theft, and certain water damage. The policy also includes personal liability coverage, which protects you if someone is injured inside your unit or if you accidentally damage someone else’s property. For example, if a guest slips and falls in your kitchen, liability coverage can help pay their medical bills or legal fees. Liberty Mutual suggests coverage of $15,000 for personal belongings and $100,000 in liability is often sufficient, though your specific needs depend on the value of your possessions and your risk tolerance.
Dwelling Coverage for Interiors
Unlike a standard homeowners policy, condo insurance provides dwelling coverage that starts from the drywall inward. This means it covers the interior walls, floors, ceilings, built-in cabinets, countertops, and any improvements or upgrades you have made. If a fire damages your kitchen cabinets and flooring, the dwelling portion of your HO-6 policy would pay to repair or replace them. The association’s master policy pays for everything outside your unit, including the building’s frame, roof, and common hallways. Understanding this split is crucial because a gap can leave you paying for major repairs out of pocket.
Why Condo Insurance Costs More in Florida
Florida condo owners pay significantly higher premiums than the national average. According to NerdWallet, the average annual cost of condo insurance in Florida is $995. This is more than twice the U.S. average. Several factors drive these higher rates. Fewer insurance companies are willing to write policies in Florida, limiting competition. Inflation has raised the cost of building materials and labor. Most notably, increased insurer scrutiny followed the 2021 Surfside condominium collapse, which heightened awareness of structural risks and led to stricter underwriting standards across the state. Miami property owners should anticipate rates well above $995 because the Florida average includes lower-cost inland areas, but the research pack does not provide a specific Miami average.Type your paragraph here.
Understanding Gaps Between Master Policy and (HO6)
The most common mistake condo owners make is assuming the association’s policy covers everything. It does not. The master policy pays for damage to the building’s exterior structure, common areas like hallways and elevators, and the land. It does not cover your personal property, interior fixtures, or personal liability. For example, if a pipe bursts inside your unit and damages your hardwood floors and sofa, the association’s policy will generally not pay for those repairs. Your HO-6 policy would handle the interior damage and personal property. Some master policies have a "walls-in" endorsement that extends coverage to interior finishes, but this varies widely. Review your association’s declaration and ask your insurance agent to help you identify any gaps.
How to Lower Your Condo Insurance Premium
Given Florida’s high rates, finding ways to reduce your premium is important. Bundling your condo and auto insurance with the same carrier can yield significant savings. State Farm offers bundling savings up to $1,429, and Progressive provides an average discount of 7% on the auto portion. Paying your annual premium in full instead of monthly can also lower your cost with some providers. Installing a burglar alarm, smoke detector, or water leak sensor may qualify for additional discounts. Finally, if your building has updated electrical, plumbing, or a newer roof, be sure to share that information with your insurer, as older infrastructure can increase rates.
Is condo unit insurance required by Florida law?
Florida law does not explicitly require individual condo owners to carry an HO-6 policy. However, most mortgage lenders require it, and your condo association’s bylaws may also mandate a minimum amount of coverage. Even if it is not required, buying a policy is strongly recommended to protect your personal property and assets.
What happens if I don't have condo insurance?
Without an HO-6 policy, you are personally responsible for all costs related to interior damage, theft, and liability claims. If a guest is injured in your unit, you could face a lawsuit without liability protection. Additionally, your association may charge you for damage that originates in your unit but affects common areas, and you would have no coverage to pay those costs.Type your paragraph here
Frequently Asked Questions
Is condo unit insurance required by Florida law?
Florida law does not explicitly require individual condo owners to carry an HO-6 policy. However, most mortgage lenders require it, and your condo association’s bylaws may also mandate a minimum amount of coverage. Even if it is not required, buying a policy is strongly recommended to protect your personal property and assets.
What happens if I don't have condo insurance?
Without an HO-6 policy, you are personally responsible for all costs related to interior damage, theft, and liability claims. If a guest is injured in your unit, you could face a lawsuit without liability protection. Additionally, your association may charge you for damage that originates in your unit but affects common areas, and you would have no coverage to pay those costs.
How much condo insurance do I need?
Start by calculating the value of your personal belongings and the cost to rebuild your interior finishes. Liberty Mutual suggests $15,000 for belongings and $100,000 in liability as a baseline, but you may need more if you own expensive jewelry, electronics, or art. Also consider your deductible: a higher deductible lowers your premium but means more out-of-pocket expense on a claim.
Can I bundle condo insurance with my car insurance?
Yes, bundling condo and auto insurance is common and can lead to substantial discounts. State Farm offers up to $1,429 in combined savings, and Progressive averages a 7% discount on the auto policy. Ask your agent to compare multi-policy quotes from several carriers to find the best overall value.
What does the condo association’s master policy cover?
The master policy covers the building’s exterior structure, common areas such as lobbies, hallways, and recreational facilities, and often the original interior construction up to the drywall. It does not cover your personal property, interior upgrades, or personal liability. Always review the master policy’s "bare walls" or "all-in" type to understand exactly where your coverage begins.Condominium ownership in Miami brings unique risks, from hurricanes to liability claims. A well-chosen HO-6 policy paired with a thorough understanding of your association’s master coverage can protect your finances and give you peace of mind. To find the right policy for your situation, compare quotes from multiple providers and work with a local independent agency that knows the Miami market.
WE WELCOME ALL CONDO UNIT INSURANCE INQUIRIES